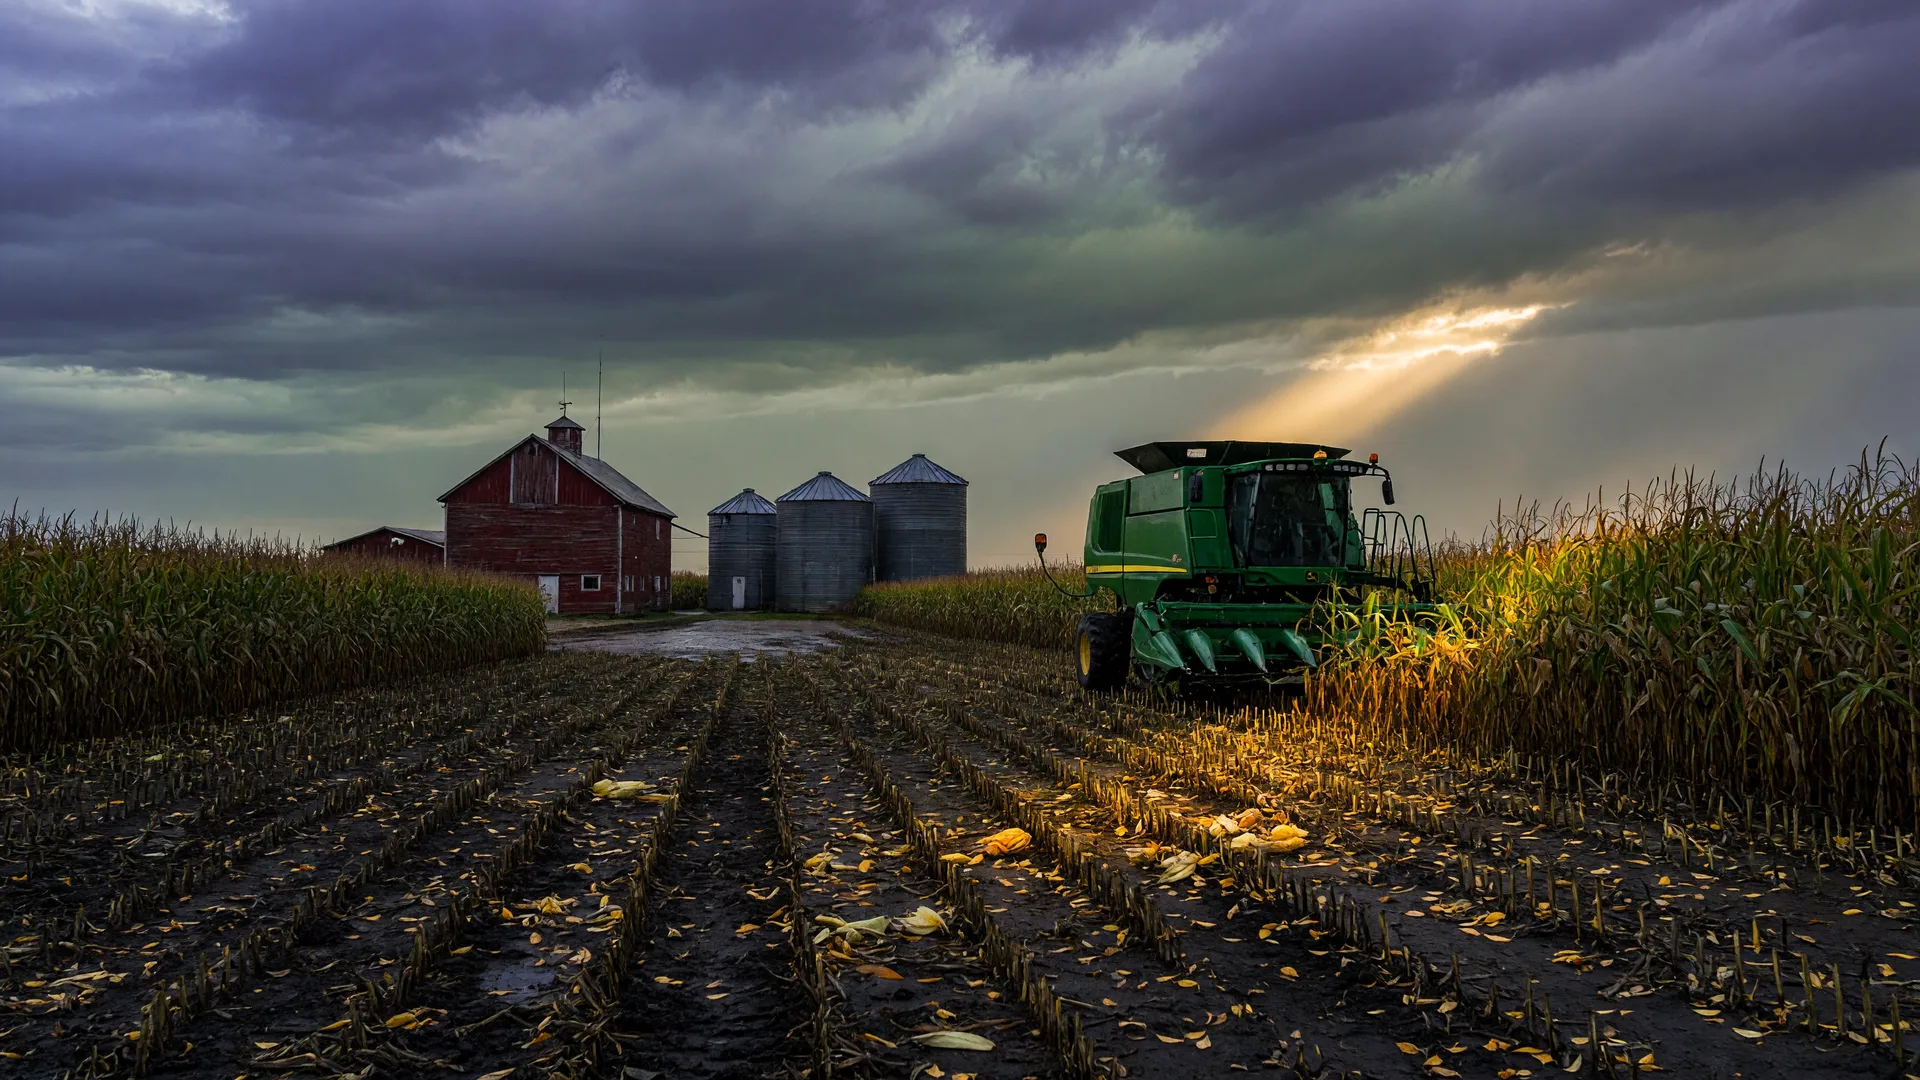
Wednesday was a report-day gut check and the tape read it straight. The USDA Quarterly Grain Stocks report put 2.095 billion bushels of old-crop corn in the bin as of September 1, roughly 170 million bushels above the average pre-report guess and higher than every estimate in the range, and December corn paid for it with a 21 1/4-cent slide to $5.00 3/4. Cattle shrugged and rallied on that cheaper corn, with October live up $1.45 to $218.67, while soybeans and wheat faded with the complex. Here is the straight talk on the last 24 hours of trading and the next 48.
Cattle
Wed Sep 30 close: Oct live $218.67/cwt, up $1.45. Dec live $222.70, up $1.90. Oct feeder $336.42/cwt, up $2.77
What Happened
Wednesday's cattle close was a rally built on cheaper corn. October live cattle settled up $1.45 at $218.67, December live cattle gained $1.90 to $222.70, and October feeders led the way again, up $2.77 to $336.42, after front months were up $2.17 to $2.60 at mid-session. The move left October live within 20 cents of Friday's $218.87 and December live at its best close in the front complex this week. Tuesday had been the sideways day, with October live down 22 cents to $217.22 and December unchanged at $220.80.
Cash stayed quiet, the same story it has been all week. USDA's LM_CT113 morning report showed just 945 head of negotiated cash purchases and 15,592 head of grid-base sales Wednesday, and Cassie Fish of The Beef put the week-to-date negotiated total at 3,403 head by Wednesday afternoon, most of it Nebraska dressed at $348 to $350, steady to a little softer than a week ago. Iowa had traded 545 head. Wednesday's Fed Cattle Exchange online auction moved no sales on the 1,586 head offered.
The reason the kill is not keeping up is still labor. The Ag Center's Cattle Report put daily federally inspected slaughter near 95,000 head against a normal 105,000 to 110,000 pace, and Cassie Fish ties the shortfall to ICE enforcement disruption in western Kansas and heavy absenteeism at major fed cattle plants. Barchart had the week-to-date federally inspected kill down about 2,000 head from last week and roughly 29,845 head below the same week in 2025. The demand side is doing its part: Drovers' Profit Tracker from Sterling Marketing, for the week of September 26, shows packers retaining margins while unhedged feedlot margins erode on high break-evens, with record-heavy carcass weights bridging the supply gap and cull cow values sliding seasonally from a $187 spring peak to about $154 in late September. Drovers' Dave Weaber of Terrain still projects cattle slaughter 4 to 6 percent lower and beef production 2.5 to 5 percent lower than 2025, with record imports, heavier weights, and resilient demand keeping prices at historic highs, and Drovers keeps flagging the tight feeder supply, with the national calf crop down about 500,000 head from a year ago. The CME Feeder Cattle Index stood at $338.77. Scott Shellady's daily Cow Guy Close on RFD-TV keeps the headline tape in front of the trade every afternoon, and the slaughter-labor story has been the headline all week.
Next 48 Hours Outlook
The next two sessions are about cash cattle finally printing against a disrupted kill. Show lists are the tell: larger lists normally argue for lower money, but packers still need cattle and the labor story is pulling slaughter capacity the other way. Thursday's USDA weekly export sales report, due at 8:30 a.m. Eastern, gives the next read on beef demand, and Friday's direct trade sets the tone into the weekend. The supply math underneath has not changed: a smaller calf crop, tight feeder supplies, and a kill running behind normal. Any soft cash print this week is a routing problem, not a demand problem.
Corn
Wed Sep 30 close: Dec contract $5.00 3/4/bu, down 21 1/4 cents on the USDA stocks surprise; Thu Oct 1 early trade near $5.01 1/2, up about a cent
What Happened
Wednesday belonged to the USDA Quarterly Grain Stocks report, and it was a corn story. Old-crop corn stocks totaled 2.095 billion bushels as of September 1, up 35 percent from 1.551 billion a year earlier, the largest September 1 carryover in seven years, about 170 million bushels above the roughly 1.924-billion-bushel average guess and above the top of the 1.860 to 2.005 billion pre-report range. DTN called the report bearish for corn, and December futures took the hit, sliding 21 1/4 cents to settle at $5.00 3/4 after opening near $5.22. Thursday's early trade found a modest recovery, December corn near $5.01 1/2, up about a cent.
The week before, December corn had been parked near $5.28 1/4, the strongest territory in three years, so the report knocked the whole complex off its perch. What has not changed is the demand story. Reuters notes a record pace of export sales and robust ethanol demand are keeping a floor under prices, and China agreed at the September 28 summit to lower tariffs on U.S. agricultural imports back to most-favored-nation levels, even though corn still saw end-of-summit selling before the stocks report landed. The other variable is harvest, and it is wet: 1.5 to 4-plus inches of rain are in the forecast for eastern Nebraska, northern Illinois, much of Iowa, and parts of Texas, Oklahoma, and Kansas, which is exactly the belt that needs to combine, while NOAA's 8-to-14-day outlook points to drier conditions returning October 6 through 12. Advance Trading's Brian Basting has been telling producers to reward sales on these rallies, with hedge-to-arrive or cash sales that keep upside open, and Joe Davis of Futures International points to the rainfall slowing fieldwork. Rural Radio's own pre-summit read, from September 23, had corn and soybeans backing away from the top of their ranges with analyst Arlan Suderman skeptical a China deal would materialize.
Next 48 Hours Outlook
The stocks report cleared the table, so the next 48 hours come down to demand and weather. Thursday's USDA weekly export sales report, due at 8:30 a.m. Eastern, is the first check on whether the record sales pace keeps rolling, and the wet-belt forecast keeps harvest risk on the board into the weekend, with the drier window still expected October 6 through 12. Watch whether Thursday's bounce holds, and remember Basting's advice: rallies are for rewarding sales, not for holding a whole year's grain in the bin hoping for the next headline.
Soybeans
Wed Sep 30 close: Nov contract $12.93/bu, down 4 3/4 cents after fading an early gain
What Happened
November soybeans settled at $12.93 Wednesday, down 4 3/4 cents and near the day's low after opening higher. The September 1 stocks number was actually friendly on its face, 315 million bushels, down 3 percent from 325 million a year earlier and below the roughly 323-million-bushel average guess, but beans could not hold it. Fund and technical selling plus the losses in corn and wheat dragged the complex lower.
The headline that matters is still China. Beijing retained a 10 percent tariff on U.S. soybeans after the September 28 Trump-Xi summit, and Reuters reports China's buying is likely to trail off on weak animal-feed demand and negative crush margins: state-run firms have bought about 13.7 million metric tons of U.S. beans since the May trade deal, but private crushers have not followed. On the supply side, harvest was 17 percent complete as of September 27, in line with the five-year average, but recent Midwest rains have slowed combining and tightened old-crop supplies, which is why cash bids have been running sharply higher. Export inspections rose to about 1.15 million tons from 769,698 the week before, and USDA has confirmed fresh new-crop sales to China.
Next 48 Hours Outlook
Beans are a Beijing headline trade all over again. The next 48 hours turn on whether the 10 percent tariff call chills private Chinese crushers further, and on Thursday's weekly export sales report for the demand read. The supportive undercurrent is the tight old-crop basis: as long as cash bids stay firm, the board has a reason to recover, and beans spent most of September above $13, closing at $13.19 on September 25 before the summit and report unwind. A steadying corn market and a decent export print puts the $13 line back in reach; another day of China headlines keeps the grind toward the lows going.
Wheat
Wed Sep 30 close: Dec Chicago SRW near $6.75 1/4/bu, down about 17 cents, a fourth straight weekly decline
What Happened
December Chicago soft red winter settled around $6.75 Wednesday, down about 17 cents on the day, roughly 2.5 percent, part of a fourth straight weekly decline. The contract now sits about 12 percent below its September 2 three-year high of $7.95. The September 1 all-wheat stocks number, about 1.85 billion bushels, down 14 percent from 2.134 billion a year earlier and essentially in line with the average guess, was a neutral non-event, and winter wheat futures still faded 9 to 13 cents on the report day.
The driver is Black Sea hope. Secretary of State Marco Rubio said Ukraine and Russia have voiced interest in a limited ceasefire covering grain and energy targets, and the trade keeps pricing in a revival of Black Sea exports even though cargo movements remain disrupted. Ukraine's August exports were down about 58 percent from a year earlier, with 801,000 metric tons moving in the first 25 days of September versus 1.52 million metric tons a year ago, and roughly 25 percent of Russia's grain moves through shallow Sea of Azov ports that stay vulnerable to attacks. USDA has raised Russian ending stocks because not all of that wheat is expected to leave the region. On the demand side, U.S. wheat export sales look thin, with traders looking for only 250,000 to 450,000 metric tons of bookings in the week of September 24, and a firmer dollar makes U.S. wheat less competitive. Rural Radio's Arlan Suderman has been the voice of caution on a quick deal, and that skepticism is worth remembering when the headline machine says peace is one signature away.
Next 48 Hours Outlook
Wheat is a ceasefire headline trade, full stop. The next 48 hours ride on whether the limited Black Sea deal talk produces anything real: a deal that actually moves cargoes keeps grinding this market lower, while stalled talks snap the premium back in a hurry. The $7.00 line is now overhead resistance after Monday's break below it. Thursday's export sales report answers whether the demand side is stabilizing, but for now the ocean moves the quote, not the spreadsheet.
What This Means for
The Bottom Line
Wednesday's USDA stocks report was the event of the week: old-crop corn at 2.095 billion bushels knocked December corn down 21 1/4 cents to $5.00 3/4, and the complex followed, with November soybeans at $12.93 and December wheat around $6.75. Cattle went the other way on cheaper corn, with October live up $1.45 to $218.67 and October feeders up $2.77 to $336.42. The next 48 hours come down to Thursday's export sales report, the wet-belt harvest forecast, China's tariff call on beans, and the Black Sea ceasefire wire. For Wisconsin farm and land sellers, the through-line is unchanged: cattle fundamentals stay tight, cash soybean bids stay firm, and land values held their ground through the first half of 2026. If you have been thinking about listing, the fall window is open and the buyers are real.
I watch these markets every day because they tell me what the buyers I work with are thinking. If you want an honest read on what your farm or land is worth in this market, give me a call. I will walk your ground with you and tell you straight what I see.
Read More on the Site
This update lives under our Cattle and Cash Crops section, where you can find deeper guides on cattle property, crop land, and what Wisconsin rural land is really worth.