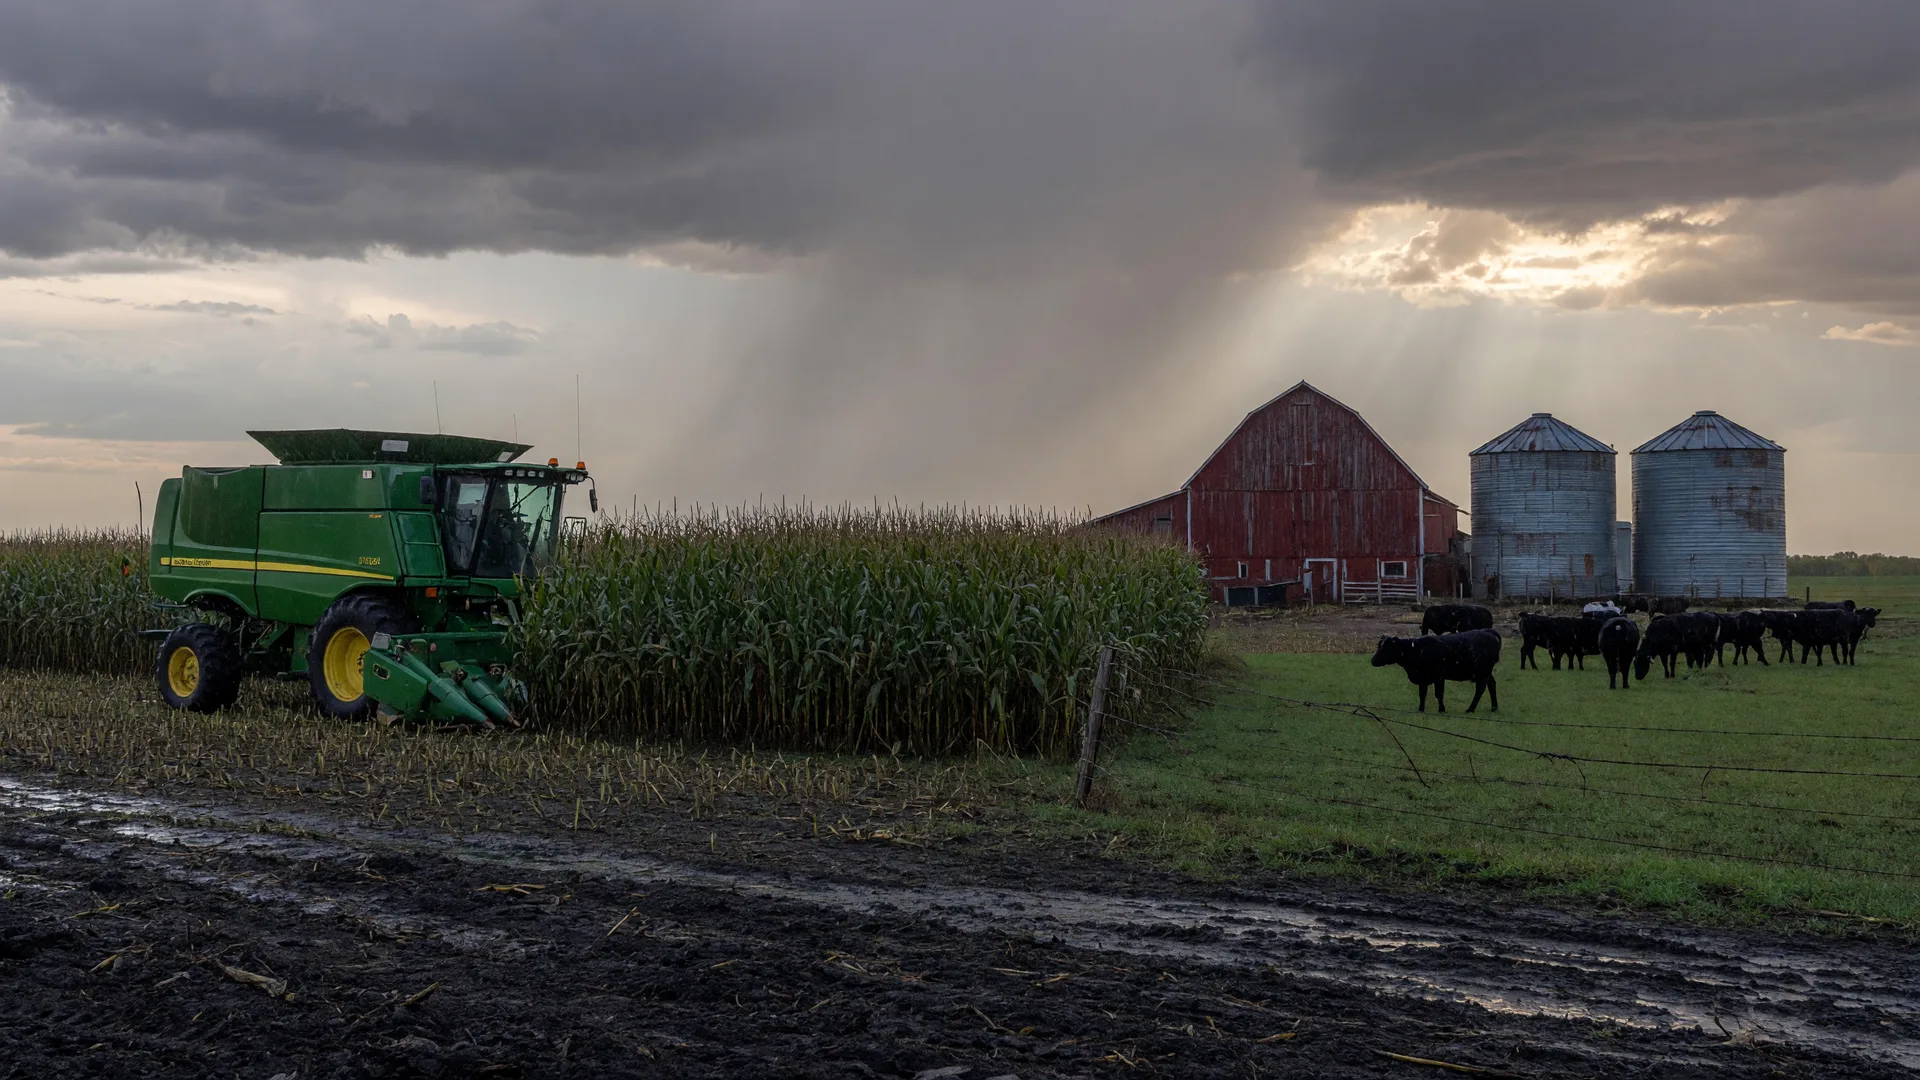
Friday was the week's gut check and the tape came off the highs. December live cattle fell $1.70 to $221.47 as cash trade softened, November feeders dropped $5.20 to $331.15, December corn slipped 4 1/2 cents to $4.97 3/4, and November soybeans ground down 5 3/4 cents to $12.78 1/4, near a five-week low, after China's tariff deal left whole beans out. December Chicago wheat held near six-week lows at $6.83 on Black Sea ceasefire talk. Here is the straight talk on the last 24 hours of trading and the next 48.
Cattle
Fri Oct 2 close: Dec live $221.47/cwt, down $1.70. Nov feeder $331.15/cwt, down $5.20
What Happened
Friday's cattle close was a pullback on softer cash. December live cattle gave back $1.70 to settle at $221.47 after Thursday's 47-cent gain to $223.17, and November feeders gave up the most, down $5.20 to $331.15 after Thursday's $2.05 advance to $336.35. The cash market did the talking: northern cash live trade was near $220 per hundredweight, about $2 under a week ago, with southern cash near $225, and Don Roose of US Commodities read the week as cash softening into the close. Thursday had been the rally day, with December live up 47 cents and feeders up $2.05, so the week finished about where it started.
The supply story underneath has not changed. Drovers reports 2026 total cattle slaughter running about 8.7 percent below a year ago through mid-September, with beef cow slaughter down about 13.7 percent, numbers Oklahoma State's Derrell Peel has been tracking all year. Cull cow prices have been sliding too, down roughly $30 per hundredweight in some regions after Southern Plains cull cows peaked at $187 this spring. Drovers' Joe Kooima says the cattle charts look "more friendly" after higher weekly closes, but he is not ready to say the funds are coming back to the buy side. Scott Shellady's Cow Guy Close on RFD-TV keeps the daily tape in front of the trade every afternoon, and the cash-versus-kill story has been the headline all week.
Next 48 Hours Outlook
Monday and Tuesday come down to cash. Friday's softer print sets the tone, and with slaughter running well behind year-ago levels on a smaller herd, the question is whether packers step in or sit on showlists. The front months are doing the work right now, so the cash trade and the contract roll will move the board more than fund flows. Watch whether November feeders can hold $330 after Friday's $5.20 spill. The bigger report, Cattle on Feed, does not land until Friday, October 23, so the next two sessions are all about the cash tape and the kill.
Corn
Fri Oct 2 close: Dec contract $4.97 3/4/bu, down 4 1/2 cents, a third straight close under the 50-day line
What Happened
December corn settled at $4.97 3/4 Friday, down 4 1/2 cents, after Thursday's modest 1 1/2-cent bounce to $5.02 1/4 off a six-week low. The contract is down about 50 cents, roughly 9 percent, from the September 2 three-year high of $5.49 1/2, and Friday marked a third straight close under the 50-day moving average near $5.07 1/4. The USDA grain stocks hangover is still on the board, and export demand is not picking up the slack: net 2026/27 corn sales came in at 536,000 metric tons for the week, disappointing for the second week in a row and near the low end of trade expectations, per the Brock Report.
The wildcard is the western Corn Belt wetness. USDA had corn 18 percent harvested as of September 27, a point ahead of last year and right at the five-year average, but widespread wetness in the western Corn Belt has brought quality degradation, sprouting, low test weights, and toxin concerns. The good news is the forecast: forecasters project a 10-to-15-day stretch of dry, mild weather once the final rain wave clears, which would open an ideal fieldwork window through mid-October. farmdoc's WILLAg Radio Week 40 review, out October 4, calls national corn yield adjustments the primary wildcard on that wetness, so the combine will write the next chapter, not the board.
Next 48 Hours Outlook
Monday's trade is about the forecast. If the dry window holds, harvest pace accelerates in the week of October 5 and the market has to find a home for the crop coming off. Watch whether December corn can reclaim $5.00 after Friday's close under it, and remember the October WASDE lands Friday, October 9 at noon Eastern, with the October Crop Production report alongside it. That is the next real headline for corn, and the yield question from the wet belt is the number everyone is waiting on.
Soybeans
Fri Oct 2 close: Nov contract $12.78 1/4/bu, down 5 3/4 cents, near a five-week low
What Happened
November soybeans settled at $12.78 1/4 Friday, down 5 3/4 cents and near a five-week low, after Thursday's 9-cent drop to $12.84 made new lows for the move. CME Group notes it is the lowest close since August 27, with the market monitoring potential fund long liquidation after a record September build. The disappointment is China: the late-September trade deal cut Beijing's 10 percent reciprocal tariffs on many U.S. agricultural goods but left whole soybeans out. Analysts are calling it what it is. Susan Stroud of No Bull Ag called the exclusion "a lump of coal," Chip Nellinger of Blue Reef Agri-Marketing says the market is disappointed China did not lower the tariff on beans, and Oliver Sloup of Blue Line Futures says funds were in liquidation mode, cutting risk exposure with spillover weakness in corn.
The demand side is not all bad. Weekly U.S. soybean export sales jumped to about 1.03 million metric tons for 2026/27, including 589,400 tonnes to China, and the American Soybean Association says China committed to buying a minimum of 25 million metric tons of U.S. soybeans annually from 2026 through 2028. Harvest is 17 percent complete, matching the five-year average, with 75 percent of the crop dropping leaves and 58 percent rated good to excellent, and a drier Midwest outlook should let combining catch up after a wet late summer.
Next 48 Hours Outlook
Beans are a fund-flow and Beijing trade. The next two sessions show whether the liquidation has run its course around $12.75, and whether private Chinese crushers step in despite the tariff after the state buyers did the heavy lifting. The 25-million-ton annual commitment is a floor under the demand story, but the market wants to see actual private buying, not promises. Thursday's export sales report gives the next read, and the October WASDE on Friday resets the yield and carryout math. A steadying corn market would help beans hold the line.
Wheat
Fri Oct 2 close: Dec Chicago SRW $6.83/bu, up 1/4 cent, near six-week lows
What Happened
December Chicago soft red winter wheat settled at $6.83 Friday, up a quarter cent and basically unchanged, hovering near six-week lows after wheat broke below $7.00 for the first time in a month in late September on Black Sea corridor talk. Kansas City December hard red winter fell 2 1/4 cents to $7.35 1/4, while Minneapolis December spring wheat gained 1 1/4 cents to $6.98. A Saudi import tender for 535,000 metric tons for November-December delivery lifted demand sentiment, but a firmer dollar capped the gains.
The Black Sea headline machine is running again. Türkiye and the UN brokered a new round of Ukraine-Russia talks on a Black Sea ceasefire to protect grain ships, launched after a closed-door UN General Assembly meeting in late September, but Ukraine says it sees no realistic near-term truce covering Black Sea grain exports, with workarounds moving only about 45 percent of required shipments. The supply reality underneath: Ukrainian strikes have taken more than 90 percent of Russia's grain export capacity in the Azov-Black Sea basin offline, and SovEcon's Andrey Sizov says practically all Russian grain exports through the basin are at a standstill. That is why the trade keeps paying attention to every round of ceasefire talk even as it sells the premium on the headlines.
Next 48 Hours Outlook
Wheat is a ceasefire headline trade, full stop. The next two sessions ride on whether the Türkiye-UN brokered talks produce anything real: a deal that actually moves cargoes keeps grinding this market lower, while stalled talks snap the premium back in a hurry. The Saudi tender shows real demand is out there, and Thursday's export sales report answers whether U.S. wheat is catching any of it. For now the ocean moves the quote, not the spreadsheet.
What This Means for
The Bottom Line
Friday's close was a pullback across the board: December live cattle down $1.70 to $221.47 on softer cash, November feeders down $5.20 to $331.15, December corn down 4 1/2 cents to $4.97 3/4, November soybeans down 5 3/4 cents to $12.78 1/4 near five-week lows, and December wheat flat at $6.83 near six-week lows. The next 48 hours come down to cash cattle, the dry-window forecast for harvest, fund liquidation in beans, and the Black Sea ceasefire wire, with the October WASDE waiting on Friday. For Wisconsin farm and land sellers, the through-line is unchanged: the cattle herd stays tight, well-drained Wisconsin ground gets attention from a wet Corn Belt, and land values held their ground through the first half of 2026. If you have been thinking about listing, the fall window is open and the buyers are real.
I watch these markets every day because they tell me what the buyers I work with are thinking. If you want an honest read on what your farm or land is worth in this market, give me a call. I will walk your ground with you and tell you straight what I see.
Read More on the Site
This update lives under our Cattle and Cash Crops section, where you can find deeper guides on cattle property, crop land, and what Wisconsin rural land is really worth.